home insurance: The Best Guide to Protecting Your Property
Purchasing a residential property in the United States represents one of the most substantial financial and emotional milestones of an […]
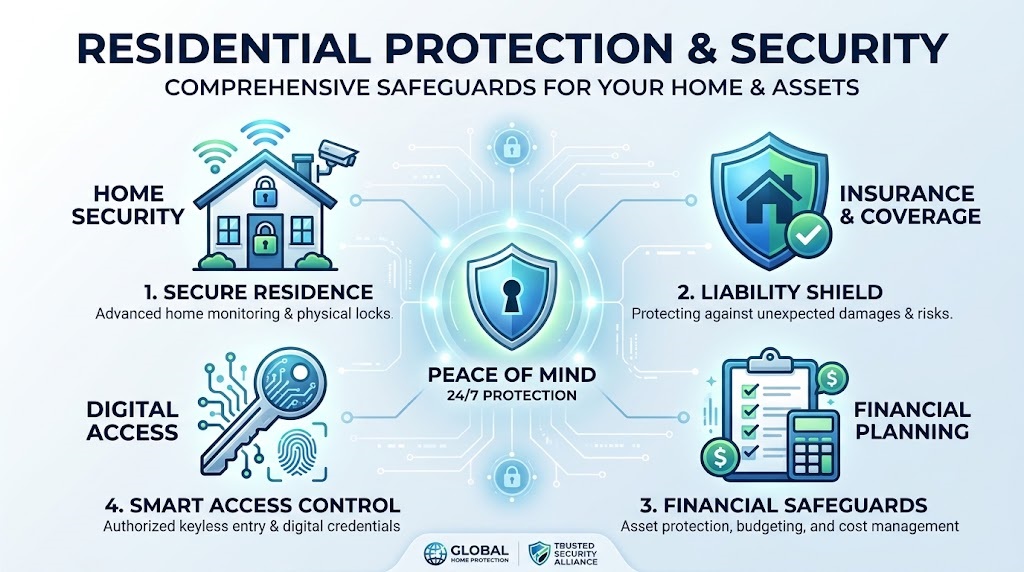
Purchasing a residential property in the United States represents one of the most substantial financial and emotional milestones of an individual’s life.
Beyond the brick, mortar, and architectural design, a house serves as a safe haven for your family and the foundation of your long-term personal wealth.
However, unexpected disasters—ranging from destructive severe thunderstorms and accidental kitchen fires to sudden plumbing pipe bursts—can threaten your investment overnight.
Securing a comprehensive, reliable home insurance policy is not merely an optional recommendation or a minor administrative hurdle mandated by mortgage lenders.
It is an absolute financial shield that guarantees your hard-earned assets remain completely protected against the unpredictable perils of daily life.
Navigating the modern insurance market requires a clear understanding of coverage limits, deductible structures, and policy exclusions to avoid costly surprises during a crisis.
In this comprehensive guide, we will explore the essential components of residential coverage, examine current market cost trends, and share expert strategies.
Understanding the Core Components of Coverage
A standard home insurance policy is actually a multi-faceted contract combining several distinct types of financial protection into a single package.
Many American homeowners mistakenly assume that their policy covers every imaginable disaster, only to discover painful gaps when filing a major claim.
To build an impenetrable safety net around your property, you must understand what each specific section of your policy is designed to cover.
Dwelling Protection and Structures
The primary section of your policy, known as dwelling coverage, protects the physical structure of your house, including walls, roof, and foundation.
When calculating how much dwelling coverage you need, insurance experts recommend evaluating the estimated rebuilding cost rather than the real estate market value.
If a catastrophic fire completely destroys your residence, your home insurance payout must be sufficient to cover current local construction labor and material expenses.
Personal Property and Liability Protection
Beyond the physical walls, your policy also extends financial protection to your interior belongings, such as furniture, electronics, and clothing.
Furthermore, personal liability protection shields your personal financial assets if a guest slips on your walkway or a visitor is injured on your property.
Carrying adequate liability limits within your home insurance framework is vital to protect your savings from unexpected legal judgments and medical lawsuits.
Key Factors Influencing Your Annual Premiums
Insurance carriers evaluate a vast array of statistical risk variables to determine the exact annual premium you will pay for your policy.
Understanding these underlying pricing mechanisms empowers you to make smart property improvements that can directly lower your monthly insurance expenditures.
From regional weather patterns to the physical age of your home, every single detail matters significantly to underwriters.
Geographic Location and Weather Risks
Where your property is physically located plays a massive role in dictating the baseline cost of your annual home insurance premiums.
Properties situated in coastal zones vulnerable to hurricanes, regions prone to frequent wildfires, or Midwestern states plagued by tornadoes face much higher rates.
Carriers must price policies to reflect the high probability of regional catastrophic loss, making location the single largest cost driver.
Home Age, Roof Condition, and Claims History
The structural age and maintenance history of your residence are scrutinized closely by insurance underwriters before approving your final policy terms.
Homes with outdated electrical wiring, aging plumbing networks, or a roof past its prime warranty window carry significantly higher risk profiles.
Additionally, filing multiple insurance claims within a short timeframe can cause your home insurance provider to hike your rates or label you high-risk.
Choosing Between Replacement Cost and Actual Cash Value
When reviewing your policy documents, one of the most critical decisions involves selecting how your insurance company calculates payout values for damaged items.
Understanding the profound financial difference between Replacement Cost Value (RCV) and Actual Cash Value (ACV) can save you thousands of dollars.
Making an informed choice ensures you are never forced to pay massive out-of-pocket expenses following a devastating household disaster.
The True Benefits of Replacement Cost
Replacement Cost coverage ensures that if your roof or living room furniture is destroyed, the insurer pays what it costs to buy brand-new items.
While this premium tier costs slightly more upfront, it provides absolute peace of mind by preventing steep depreciation deductions from cutting your payout.
Most financial advisors strongly recommend opting for full replacement cost structures when setting up your primary home insurance portfolio.
Understanding Actual Cash Value Limitations
Actual Cash Value policies factor in severe depreciation over time, meaning the payout reflects what your used, older items were worth at the time of loss.
If a five-year-old appliance is ruined, an ACV policy only gives you the depreciated garage-sale value, leaving you to cover the gap.
Reviewing your home insurance declarations page carefully guarantees you know exactly how your insurer calculates reimbursements during stressful claims.
Smart Strategies to Lower Your Monthly Costs
With national insurance premiums experiencing steady upward pressure due to rising construction and labor costs, finding ways to save is a priority.
Fortunately, homeowners can implement several highly effective, proven strategies to reduce their monthly bills without sacrificing essential protection.
Proactive risk management and policy optimization are your best tools for keeping your household budget balanced.
Bundling Policies and Increasing Deductibles
One of the easiest ways to secure immediate discounts is by bundling your home insurance with your auto insurance through the same carrier.
Insurance companies love loyalty and routinely slash ten to twenty percent off combined bills when you consolidate your household protection accounts.
Additionally, opting for a higher deductible—such as raising it from $1,000 to $2,500—can significantly lower your recurring monthly premium payments.
Installing Smart Home Safety Technology
Modern technological advancements have given homeowners incredible new ways to prove their low-risk status directly to insurance underwriting departments.
Installing smart water leak detection sensors, monitored burglar alarms, and automated smoke shut-off valves can earn you substantial policy discounts.
Insurance providers actively reward proactive risk mitigation, making tech upgrades a smart investment for your home insurance savings.
Frequently Asked Questions
What is the national average cost of coverage in the United States?
While rates vary wildly by state and zip code, the typical annual cost for a standard policy sits around $2,500 for moderate dwelling limits.
Does a standard policy cover damage caused by major floods or earthquakes?
No, standard policies universally exclude damage from rising ground floodwaters and seismic earthquakes, requiring separate, dedicated supplemental policies.
What should I do immediately after discovering storm damage on my property?
Document all physical damage thoroughly with clear photographs, contact your insurance provider promptly, and make temporary emergency repairs to prevent further loss.
Can an insurance company cancel my policy after I file a claim?
In most states, carriers cannot cancel mid-term without valid cause, but they can legally choose not to renew your home insurance contract at the annual renewal date.
How does the age of my roof affect my insurance rates?
Roofs older than fifteen to twenty years are often subjected to higher premiums, mandatory roof deductibles, or requirements for immediate replacement before coverage approval.
Are personal items covered when traveling away from home?
Yes, standard policies typically include off-premises theft and damage protection for your personal belongings while traveling anywhere around the world.
Conclusion
Securing your residential property with a robust, reliable home insurance policy is a fundamental pillar of intelligent financial management and family security.
While navigating deductibles, premium variations, and policy limits can initially feel complex, taking the time to understand your coverage safeguards your future.
By evaluating your true replacement costs, bundling policies, and maintaining your home proactively, you ensure optimal protection without overpaying.
Take the necessary steps today to review your current declarations page, talk with an experienced agent, and optimize your home insurance strategy.
The videos above provide additional visual breakdowns and expert insights to help you navigate policy choices and maximize your coverage efficiency.

Written by Twastia Editorial Team
Twastia Editorial Team shares practical insights about website design, SEO services, Google Ads, content marketing, social media, conversion rate optimization, and digital marketing strategy.
Last updated: Oct 24, 2026
Related posts from Twastia
Explore more useful articles from twastia.com about digital marketing, SEO, websites, ads, content, and growth strategy.