Loans Software: Best Features and Solutions for Modern Digital Lending
Managing loans involves much more than approving applications and collecting repayments. Financial institutions must verify borrower information, assess credit risk, […]
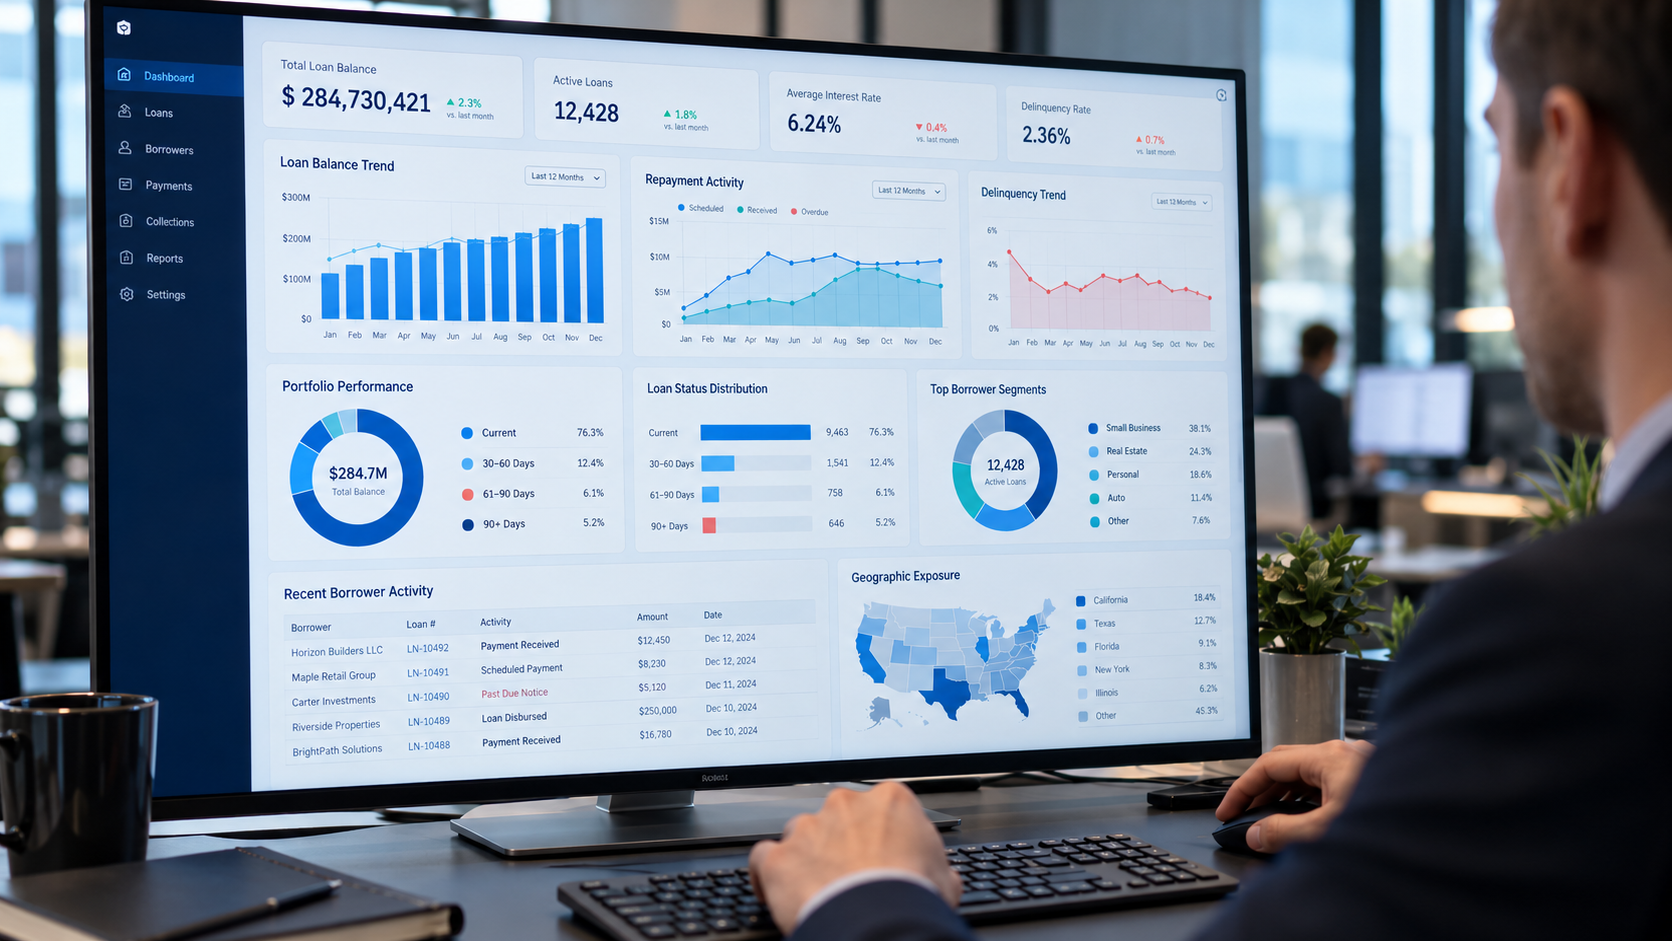
Managing loans involves much more than approving applications and collecting repayments. Financial institutions must verify borrower information, assess credit risk, maintain accurate records, monitor repayment schedules, and provide a reliable customer experience.
When these processes depend on spreadsheets, emails, and disconnected systems, lending operations can become slow and difficult to manage.
This is where loans software makes a meaningful difference.
Modern lending platforms help banks, credit unions, fintech companies, and alternative lenders organize the entire loan lifecycle in one digital environment. From receiving applications to servicing existing loans, these tools can reduce repetitive work and improve operational visibility.
However, not every lending platform offers the same capabilities.
This guide explains why loans software matters, common challenges in traditional lending, ten practical ways to improve lending operations, essential software solutions, and how to choose a platform that supports your business needs.
Why Loans Software Matters for Modern Financial Institutions
Loans software provides a centralized system for managing lending activities, borrower records, credit decisions, repayments, and operational reporting.
Traditional lending operations often involve several departments and multiple software applications. Moving information between these systems can create delays, duplicate data, and unnecessary manual work.
A modern lending management system helps coordinate these processes and provides employees with access to relevant information.
The key benefits include:
- Faster processing of digital loan applications.
- Reduced repetitive administrative work.
- More consistent credit evaluation workflows.
- Improved visibility into loan portfolio performance.
- Better organization of borrower documents.
- More efficient repayment tracking and communication.
- Greater flexibility when introducing new lending products.
These improvements are particularly valuable for organizations managing growing loan portfolios or serving borrowers across multiple locations.
Still, technology alone cannot guarantee accurate lending decisions or regulatory compliance. Effective implementation requires appropriate policies, employee oversight, data controls, and regular system evaluation.
Common Challenges in Traditional Loan Management
Before selecting loans software, financial institutions should understand the operational problems they want to solve.
1. Slow Loan Application Processing
Manual applications often require employees to collect documents, verify information, and transfer borrower details between systems.
These steps can delay lending decisions and frustrate applicants.
Digital workflows help organize submitted information and direct applications to the appropriate review stages.
2. Inconsistent Credit Assessment
Credit evaluation becomes difficult when underwriting teams rely on disconnected documents or inconsistent procedures.
A structured decisioning system can apply defined eligibility criteria and organize risk information for review.
Human oversight remains important, particularly when decisions involve unusual borrower circumstances or regulatory requirements.
3. Complicated Repayment Tracking
Tracking payment dates, outstanding balances, fees, and overdue accounts manually increases administrative pressure.
Lenders need accurate records to understand account status and communicate clearly with borrowers.
4. Limited Portfolio Visibility
Without centralized reporting, managers may struggle to understand loan performance across products or departments.
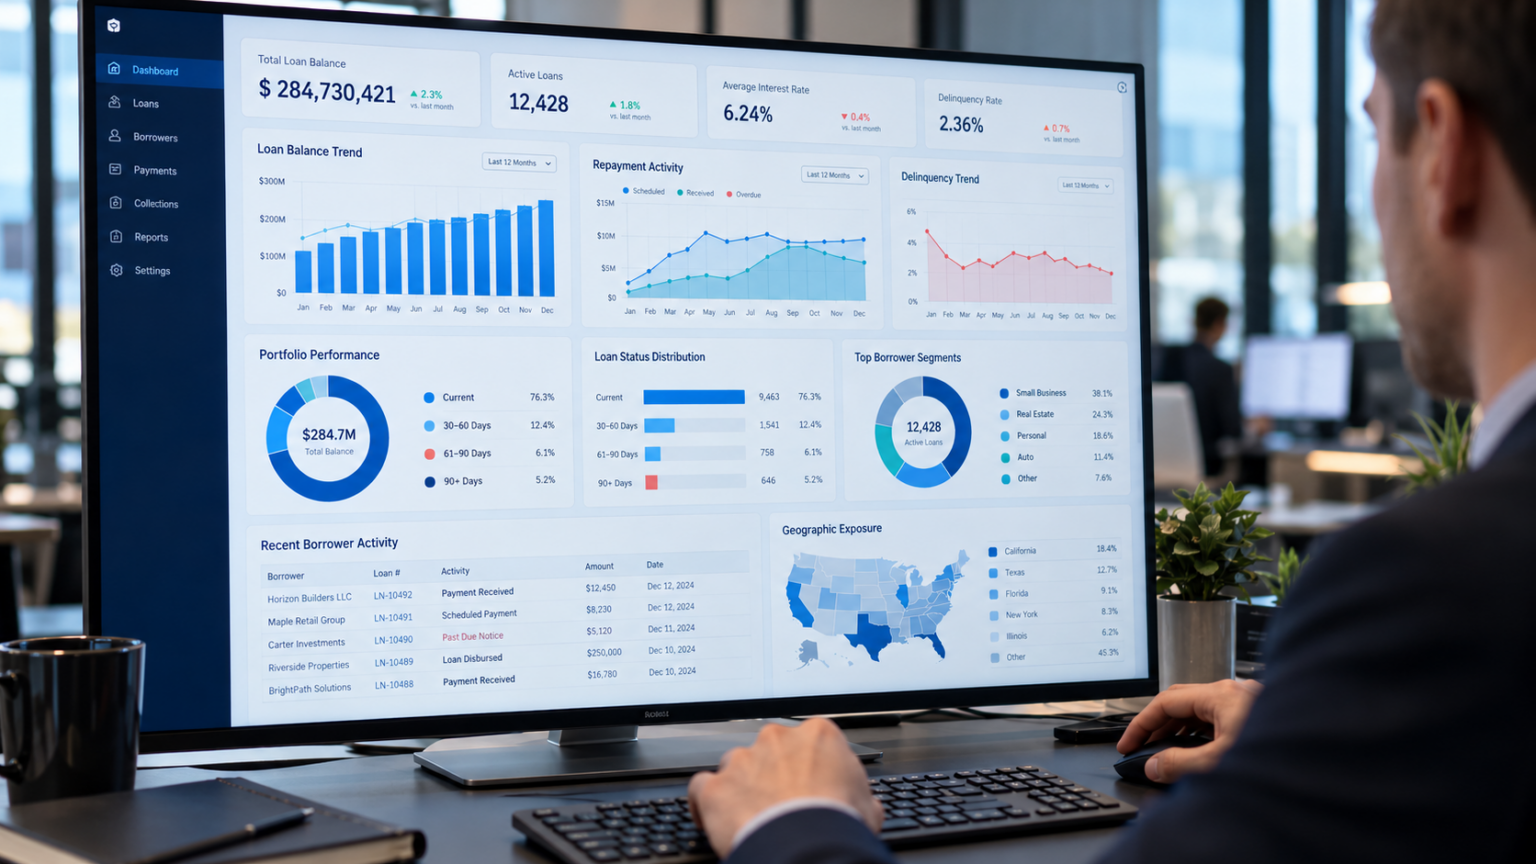
Modern lending platforms provide dashboards that make portfolio activity easier to evaluate and help teams identify emerging problems.
10 Practical Ways to Improve Lending Operations With Loans Software
Successful implementation starts with understanding how technology can improve each stage of the loan lifecycle.
1. Automate Digital Loan Applications
Digital applications allow borrowers to submit information without relying entirely on paper forms or in-person visits.
A loan application management system can collect required details, organize documents, and send applications through predefined workflows.

Digital Loan Application System
Online applications simplify the first step of borrowing by allowing applicants to submit details electronically. Lenders can configure required fields, validation rules, and document requests according to their products.
Well-designed application forms should also work smoothly on mobile devices and explain how personal information will be handled.
2. Centralize Borrower Information
Keeping borrower data in separate spreadsheets makes it difficult to maintain accurate records.
Centralized loans software can organize customer profiles, application history, documents, repayment information, and communication records.
Role-based permissions help restrict access to employees who need specific information for their work.
3. Streamline Credit Decisioning
Credit decisioning software can evaluate applications against defined lending rules and data sources.
For example, a lender may configure eligibility checks related to income, credit history, existing obligations, or other permissible criteria.

Automated Credit Assessment
Decision engines organize relevant risk information and support consistent underwriting workflows. Automated decisions should remain explainable, appropriately tested, and subject to applicable fair lending requirements.
Automation should support responsible lending practices rather than replace appropriate risk governance.
4. Improve Loan Origination Workflows
Loan origination includes the activities required to evaluate, approve, document, and issue a loan.
Loan origination software helps coordinate these stages through configurable workflows.
Employees can identify incomplete applications, review pending decisions, and monitor processing stages without relying on scattered email conversations.
5. Simplify Document Verification
Borrowers may need to provide identity documents, income records, business information, or other supporting materials.
Digital verification tools can help organize these documents and support identity checks.
However, lenders must ensure verification methods satisfy applicable requirements and maintain appropriate protections for sensitive personal information.
6. Automate Repayment Scheduling
Loan servicing requires accurate information about payment amounts, due dates, outstanding balances, and account activity.
A loan servicing platform can generate schedules based on configured loan terms and record payment transactions.

Loan Repayment Management
Automated schedules help employees monitor upcoming payments and account balances. Appropriate notifications can also remind borrowers about due dates without relying on manual follow-up.
Accurate configuration and reconciliation remain necessary because repayment calculations directly affect borrower accounts.
7. Strengthen Loan Portfolio Monitoring
Loan portfolio management tools provide a broader view of lending performance.
Managers can monitor metrics such as outstanding principal, delinquency, repayment activity, and portfolio composition.
Analyzing these indicators helps organizations identify performance trends and evaluate credit policies.
8. Improve Borrower Communication
Clear communication is important throughout the lending relationship.
Automated systems can support application updates, document requests, payment reminders, and account notifications.
Messages should be accurate, accessible, and compliant with applicable consumer protection and communication requirements.
9. Connect Lending With Existing Business Systems
Financial institutions frequently depend on customer relationship management software, payment services, accounting tools, and credit data providers.
Integration capabilities help reduce repeated data entry and improve coordination between systems.
Before implementing a new platform, organizations should review available APIs, supported integrations, data formats, and technical requirements.
10. Use Reporting to Improve Decisions
Reliable reporting helps lenders evaluate operational efficiency and identify areas requiring attention.
Dashboards may display approval rates, application processing times, delinquency trends, and repayment performance.
Regular review of these metrics helps managers understand whether workflows are delivering the intended improvements.
Best Loans Software Solutions and Essential Features
The best loans software depends on the type of lending business, its technical requirements, and the products being offered.
Several solution categories are especially valuable.

1. Loan Origination Systems (LOS)
Loan origination systems manage application intake, verification, underwriting, approval, and loan issuance workflows. They are useful for institutions that want to improve processing consistency and reduce manual application handling.

2. Loan Servicing and Management Platforms
These systems focus on active loan accounts, payment schedules, balances, account history, and servicing activities. They help lenders maintain organized records after a loan has been issued.

3. Credit Decisioning and Risk Management Tools
These solutions support underwriting rules, data evaluation, and portfolio risk monitoring. Lenders should verify that the system supports transparent decisions, suitable testing, and required compliance controls.

4. No-Code Lending Platforms
No-code solutions let organizations configure certain lending workflows without developing every component from scratch. They can be useful for institutions introducing new loan products or adjusting existing processes, although complex integrations may still require technical expertise.
Cloud-Based vs. Traditional Loans Software
Cloud-based lending platforms are increasingly used by fintech companies and financial institutions seeking flexible infrastructure.
Rather than maintaining every application on local servers, cloud-based systems can provide hosted access, configurable environments, and subscription-based services.
Traditional on-premises systems may offer greater control over certain infrastructure decisions but often require more internal maintenance.
| Cloud-Based Lending Software | Traditional On-Premises Software |
|---|---|
| Hosted infrastructure | Institution-managed infrastructure |
| Remote access where permitted | Access depends on internal configuration |
| Vendor-supported updates | Organization-managed update processes |
| Subscription or usage-based pricing is common | Licensing and infrastructure costs may apply |
| Vendor and shared security responsibilities | Greater direct infrastructure responsibility |
Neither approach automatically guarantees better security or compliance.
Organizations should evaluate encryption, access controls, disaster recovery, audit logging, vendor reliability, and data governance before making a decision.
For U.S. lenders, relevant obligations may include the Equal Credit Opportunity Act, Fair Credit Reporting Act, Gramm-Leach-Bliley Act, and applicable state requirements.
The CFPB’s May 2026 small-business lending rule revisions also extended the relevant Section 1071 compliance date to January 1, 2028, making accurate regulatory planning important for affected lenders.
Consumer Financial Protection Bureau
+1
Step-by-Step Plan for Choosing the Right Loans Software
Step 1: Define Your Lending Requirements
Identify the loan products you offer, the number of applications processed, and the operational problems you need to solve.
Consumer lending, business financing, installment loans, and lines of credit may require different workflows.
Step 2: Compare Features and Integration Options
Evaluate application processing, underwriting, servicing, reporting, security, and integration capabilities.
For example, Neofin’s loans software provides configurable lending infrastructure for digital lenders and fintech organizations. Its published capabilities include no-code loan product configuration, credit decisioning, and lending workflow automation.
neo-fin.com
+1
Step 3: Evaluate Security and Compliance
Review access controls, audit trails, data protection arrangements, and compliance-supporting features.
Ask vendors how their systems handle regulatory changes, sensitive information, and operational failures.
Step 4: Test Before Full Implementation
Start with a controlled pilot involving representative loan products and realistic borrower scenarios.
Check calculations, integrations, employee workflows, reporting accuracy, and exception handling before expanding the rollout.
Common Loans Software Mistakes to Avoid
Choosing software based only on pricing can create problems when essential features require additional integrations or expensive customization.
Another mistake is automating inefficient processes without first reviewing how they work. Poorly designed workflows may simply produce errors faster.
Lenders should also avoid assuming that built-in compliance features guarantee regulatory compliance. Legal obligations still require appropriate policies, reviews, and oversight.
Finally, employee training and data migration deserve careful attention. Even capable software can perform poorly when users lack preparation or existing records contain inaccuracies.
Frequently Asked Questions About Loans Software
1. What is loans software?
Loans software is a digital system that helps lenders manage applications, credit evaluation, loan issuance, repayments, borrower records, and lending operations.
2. Who uses loans software?
Banks, credit unions, fintech companies, commercial lenders, alternative lenders, and other financial institutions use lending software to manage different stages of the loan lifecycle.
3. What is the difference between loan origination and loan management software?
Loan origination software primarily handles applications and loan issuance. Loan management software generally supports ongoing account administration, repayment tracking, and servicing activities.
4. Can loans software automate credit approvals?
Yes. Some platforms support automated decisioning based on configured policies and relevant data. Lenders remain responsible for appropriate oversight and compliance.
5. Is cloud-based loans software secure?
Cloud-based platforms can offer strong security controls, but protection depends on vendor practices, system configuration, access management, and operational safeguards.
6. How much does loans software cost?
Pricing varies according to features, loan volume, implementation requirements, integrations, and vendor agreements. Organizations should compare total ownership costs rather than subscription fees alone.
7. Can small lending businesses use loans software?
Yes. Smaller lenders can use configurable platforms to organize borrower information, manage repayments, and improve workflows without necessarily building custom software.
8. How do I choose the best lending software?
Start with business requirements, then evaluate functionality, regulatory needs, integrations, usability, vendor support, security, and long-term costs. Test important workflows before purchasing.
Conclusion
Loans software has become an important part of modern lending operations, helping financial institutions manage applications, credit decisions, borrower information, repayments, and portfolio performance through digital systems.
For banks, credit unions, fintech companies, and alternative lenders, the right platform can reduce repetitive administrative tasks while improving visibility into lending activities.
However, choosing effective software requires more than comparing attractive dashboards or automation features. Organizations should carefully evaluate their loan products, compliance obligations, integration needs, data security, and employee workflows.
A thoughtful implementation process, supported by appropriate testing and staff training, helps lenders make better use of their technology investments.
By selecting a scalable lending solution that fits real business requirements, financial institutions can establish more organized operations and deliver a smoother borrowing experience.

Written by Twastia Editorial Team
Twastia Editorial Team shares practical insights about website design, SEO services, Google Ads, content marketing, social media, conversion rate optimization, and digital marketing strategy.
Last updated: Oct 26, 2026
Related posts from Twastia
Explore more useful articles from twastia.com about digital marketing, SEO, websites, ads, content, and growth strategy.