How to Prepare and Apply for an Auto Loan in the USA: A Complete Buyer’s Guide
Buying a vehicle is one of the largest purchases many Americans make outside of buying a home. Whether you are […]
Buying a vehicle is one of the largest purchases many Americans make outside of buying a home. Whether you are purchasing your first car, replacing an older vehicle, or upgrading to something that better fits your family, financing can significantly affect the total cost of ownership.
Most buyers do not pay the entire price in cash. Instead, they borrow money and repay it over several years.
Before applying for an auto loan, it is important to understand how lenders evaluate applications, how interest affects your total cost, and how loan terms can change your monthly payment.
A good financing decision is not simply about getting approved. It is about finding a loan that fits your budget while minimizing unnecessary interest and financial risk.
What Is an Auto Loan?
An auto loan is money borrowed specifically to purchase a vehicle.
The lender pays the seller or dealership, and the borrower repays the lender through monthly payments over an agreed period.
Most vehicle loans are secured loans. This means the vehicle itself acts as collateral.
If the borrower stops making payments, the lender may have the right to repossess the vehicle.
A typical auto loan includes several important components:
- Loan principal
- Annual percentage rate, or APR
- Loan term
- Monthly payment
- Down payment
- Fees
- Total interest paid
Understanding each part can help you compare financing offers more accurately.
How Auto Loans Work
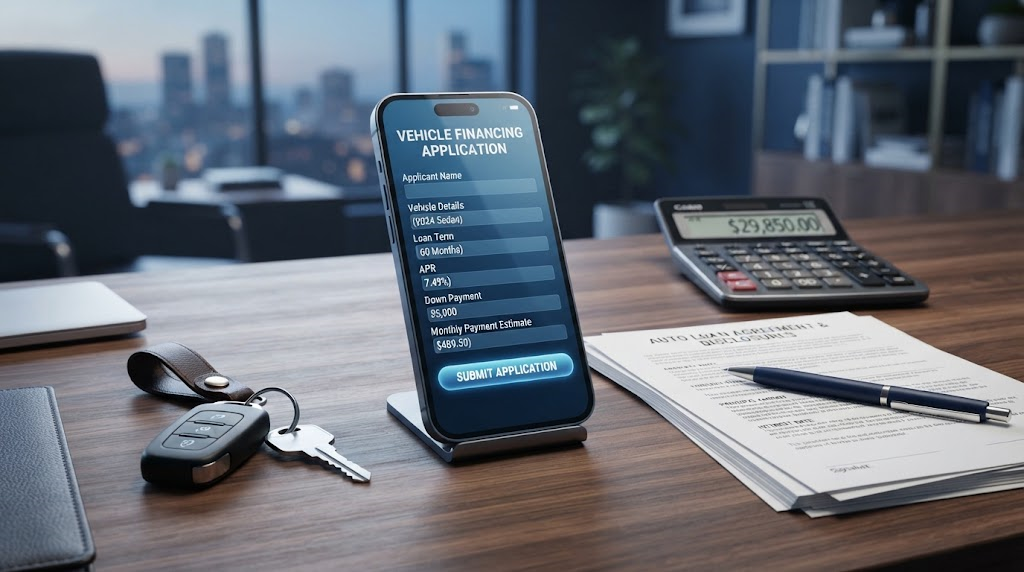
Suppose a vehicle costs $35,000.
You make a $5,000 down payment, leaving $30,000 to finance.
The lender then charges interest based on your approved rate and repayment period.
If you select a longer loan term, your monthly payment will usually be lower. However, you may pay more total interest over the life of the loan.
A shorter term generally creates higher monthly payments but can reduce overall borrowing costs.
This trade-off is one of the most important decisions in vehicle financing.
Where Can You Get an Auto Loan?
American consumers have several financing options.
Banks
Traditional banks frequently offer new and used vehicle financing.
If you already have a relationship with a bank, applying there may be convenient because the lender already has some of your financial information.
However, convenience does not necessarily mean you are getting the best rate.
Always compare offers.
Credit Unions
Credit unions are member-owned financial institutions.
They often provide competitive lending products, including vehicle loans.
Eligibility requirements vary depending on the credit union.
For qualified members, a credit union may be worth comparing against banks and dealer financing.
Online Lenders
Online lenders allow borrowers to research and apply for vehicle financing digitally.
This can make rate comparison faster and more convenient.
However, borrowers should carefully review lender reputation, fees, eligibility requirements, and loan conditions before applying.
Dealership Financing
Car dealerships commonly arrange financing directly.
The dealership may work with multiple banks or lending companies.
Dealer financing can be convenient because vehicle selection and financing happen in one place.
However, buyers should still obtain independent financing quotes beforehand.
Knowing what banks or credit unions are willing to offer gives you a benchmark when evaluating dealership financing.
Check Your Credit Before Applying
Your credit profile is one of the most important factors lenders evaluate.
Lenders generally use credit information to estimate the likelihood that you will repay the loan according to the agreement.
Before submitting applications, review your credit reports.
Check for:
- Incorrect late payments
- Accounts you do not recognize
- Incorrect balances
- Duplicate accounts
- Other reporting errors
If you find legitimate inaccuracies, resolving them before financing a vehicle may improve your application.
How Credit Scores Affect Auto Financing
Borrowers with stronger credit profiles generally have access to more favorable financing terms.
That does not mean people with lower scores cannot obtain car financing.
However, they may face:
- Higher interest rates
- Larger down-payment requirements
- Fewer lender options
- Stricter loan conditions
The interest-rate difference can become substantial over several years.
For that reason, improving your credit before purchasing a vehicle may produce meaningful savings.
Determine What You Can Actually Afford
One of the most common mistakes buyers make is focusing entirely on the monthly payment.
Dealers can often make an expensive vehicle appear affordable by extending the loan term.
For example, spreading financing over more years can reduce the monthly payment while increasing total interest.
Instead of asking only:
“What monthly payment can I afford?”
Ask:
“What total vehicle cost can I realistically afford?”
Consider the full ownership expense.
This includes:
- Loan payment
- Auto insurance
- Fuel
- Maintenance
- Repairs
- Registration
- Taxes
- Parking
- Potential depreciation
A $500 monthly loan payment does not mean the car only costs you $500 per month.
Save for a Down Payment
A down payment reduces the amount you need to borrow.
For example, if you purchase a $30,000 vehicle and put $6,000 down, you only need to finance approximately $24,000 before applicable taxes or fees.
A larger down payment can provide several benefits.
It may:
- Reduce monthly payments
- Reduce total interest
- Improve approval chances
- Lower the risk of owing more than the car is worth
However, avoid using every dollar of your emergency savings simply to increase the down payment.
Financial flexibility still matters after buying the vehicle.
Understand Auto Loan Preapproval
Preapproval can be one of the most useful steps before visiting a dealership.
When you seek auto loan preapproval, a lender reviews your financial information and gives you an indication of the amount and financing terms you may qualify for.
Preapproval helps you understand your realistic buying power.
It can also strengthen your position when negotiating with a dealership.
Instead of depending entirely on dealer financing, you arrive with an alternative financing option.
Why Shopping for Rates Matters
Small interest-rate differences can translate into hundreds or thousands of dollars over the life of a loan.
Imagine two lenders financing the same vehicle.
One offers a significantly lower APR than the other.
Even if the monthly payment difference appears small, the total repayment difference over several years can be substantial.
Compare offers from multiple lenders when practical.
Look at:
- APR
- Loan term
- Monthly payment
- Total interest
- Origination fees
- Prepayment conditions
- Other lender charges
The lowest monthly payment is not automatically the best loan.
Understand APR
APR stands for annual percentage rate.
It represents the annualized cost of borrowing and is one of the most useful numbers for comparing loan offers.
Lower APR generally means lower borrowing costs, assuming other loan conditions are similar.
Your approved APR may depend on factors such as:
- Credit history
- Credit score
- Income
- Debt obligations
- Loan amount
- Loan term
- Vehicle age
- Vehicle type
- Down payment
- Lender policies
Do not confuse APR with the vehicle’s purchase price.
They are separate parts of the transaction.
New vs. Used Car Financing
Financing conditions may differ between new and used vehicles.
New Vehicles
New cars may sometimes qualify for more competitive financing because they generally have predictable values and lower mechanical risk.
Manufacturers may also offer promotional financing on selected models.
However, new vehicles usually cost more and can experience substantial depreciation during the first years of ownership.
Used Vehicles
Used cars generally have lower purchase prices.
However, older vehicles may receive higher financing rates depending on the lender.
Some lenders also impose limits on:
- Vehicle age
- Mileage
- Loan amount
- Loan duration
Always check the lender’s used-car requirements before choosing a vehicle.
Choosing the Right Loan Term
Common vehicle financing terms can range from a few years to significantly longer repayment periods.
Long-term auto loans have become attractive because they reduce monthly payments.
However, there are important risks.
Benefits of a Shorter Loan
A shorter loan may offer:
- Faster ownership
- Less total interest
- Reduced risk of negative equity
- Earlier elimination of monthly payments
The trade-off is a higher monthly payment.
Risks of a Long Loan Term
Long loans can create situations where you owe more than the vehicle’s market value.
This is commonly called being “upside down” or having negative equity.
Vehicles generally depreciate over time.
If your loan balance decreases more slowly than the car’s value, selling or trading the vehicle can become difficult.
Documents You May Need
Lender requirements vary, but applicants may be asked to provide information such as:
- Government-issued identification
- Social Security number
- Residential address
- Employment information
- Income documentation
- Vehicle information
- Insurance information
- Down-payment details
Self-employed borrowers may need additional documentation demonstrating income.
Having your documents organized can make the application process smoother.
Debt-to-Income Ratio and Auto Loans
Lenders may examine your debt-to-income ratio, often called DTI.
This ratio compares monthly debt obligations with monthly income.
Existing obligations may include:
- Mortgage
- Rent considerations in affordability reviews
- Credit card debt
- Student loans
- Personal loans
- Existing vehicle payments
Someone earning a high income can still have difficulty qualifying for favorable financing if existing debt obligations are already very high.
Reducing unnecessary debt before applying may improve your overall financial position.
Should You Use a Cosigner?
Some borrowers use a cosigner when their own credit history is limited or weak.
A cosigner agrees to become legally responsible for the debt if the primary borrower fails to pay.
This can potentially improve approval chances.
However, cosigning carries serious financial consequences.
Missed payments may affect both individuals’ credit, and the cosigner can become responsible for the remaining balance.
Cosigning should never be treated as a casual favor.
Both parties should understand the legal and financial obligations involved.
Avoid Focusing Only on Monthly Payments
During vehicle negotiations, always separate these three discussions when possible:
- Vehicle purchase price
- Trade-in value
- Financing
Combining all three into a single monthly-payment discussion can make it difficult to understand what you are actually paying.
For example, a dealer may reduce your monthly payment by extending the financing term rather than reducing the price.
Always review the final numbers carefully.
Watch for Add-On Products
Dealership financing offices may offer additional products such as:
- Extended warranties
- Service plans
- Tire protection
- Appearance protection
- GAP coverage
- Other insurance or protection products
Some may provide value depending on your situation.
Others may substantially increase the amount financed.
Do not assume every add-on is mandatory.
Ask:
What does it cover?
How much does it cost?
Is it optional?
Can I purchase equivalent coverage elsewhere?
Understanding each item prevents unexpected increases in your loan balance.
Consider the Total Cost of the Loan
Before signing, calculate how much you will repay in total.
Consider a simplified example.
You borrow $30,000.
Your monthly payments over the full term may ultimately total significantly more than $30,000 because of interest.
The difference is the cost of borrowing.
Comparing total repayment rather than monthly payment alone gives you a much clearer financial picture.
Can You Pay an Auto Loan Off Early?
Some borrowers want to make additional payments or repay their loan early.
Check the loan agreement for any restrictions or prepayment penalties.
When extra payments are allowed and correctly applied to principal, early repayment may reduce total interest.
However, lender policies differ.
Confirm how additional payments are applied before sending extra money.
Common Auto Loan Mistakes to Avoid
Buying Before Arranging Financing
Walking into a dealership without knowing your financing options reduces your negotiating leverage.
Research lenders first.
Choosing the Longest Term Automatically
Lower monthly payments can look attractive, but long terms can increase total cost.
Ignoring Your Credit
Your credit profile can materially affect the rate you receive.
Review it before applying.
Financing Unnecessary Extras
Adding thousands of dollars in optional products can significantly increase total repayment.
Buying at the Maximum Approved Amount
A lender’s maximum approval is not necessarily the amount you should spend.
Your personal budget may justify a much lower vehicle price.
How to Improve Your Chances of Auto Loan Approval
Several steps may strengthen your application:
Improve Your Credit Profile
Pay bills on time and reduce revolving debt where practical.
Reduce Existing Debt
Lower monthly obligations can improve overall affordability.
Increase Your Down Payment
Borrowing less reduces lender risk.
Choose a Less Expensive Vehicle
A smaller loan can be easier to qualify for.
Provide Accurate Information
Income and employment details should be complete and accurate.
Consider a Qualified Cosigner
When appropriate, a financially strong cosigner may help some applicants qualify.
Frequently Asked Questions
What credit score do I need for an auto loan?
There is no universal minimum credit score for all lenders. Approval standards differ, and interest rates generally become more favorable for borrowers with stronger credit profiles.
Should I get preapproved before visiting a dealership?
Preapproval can be useful because it gives you a financing benchmark and helps establish your realistic vehicle budget before negotiating at a dealership.
Is a bank or dealership better for car financing?
Neither option is automatically better. Banks, credit unions, online lenders, and dealerships can all offer competitive financing. Comparing multiple offers is usually the strongest approach.
How much should I put down on a car?
There is no single down-payment percentage appropriate for everyone. A larger down payment reduces the amount financed, but buyers should also maintain adequate emergency savings.
Can I get an auto loan with bad credit?
Potentially, yes. Some lenders work with borrowers who have weaker credit histories. However, borrowing costs may be higher.
Does applying for several auto loans hurt my credit?
Loan applications can involve credit inquiries. Credit-scoring models may treat multiple rate-shopping inquiries differently when they occur within a limited period, but consumers should understand the scoring model and lender process involved.
What is the best loan term for a car?
The appropriate term depends on your budget, interest rate, vehicle price, and financial priorities. Shorter loans typically reduce total interest but require larger monthly payments.
Can I refinance my auto loan later?
Yes, refinancing may be possible if you qualify. Borrowers sometimes refinance when interest rates, credit profiles, or financial circumstances improve. However, fees and the remaining loan term should be evaluated before refinancing.
Conclusion
Financing a car is not simply about finding a lender willing to approve your application.
The real objective is to obtain a vehicle you can comfortably afford while minimizing unnecessary borrowing costs.
Before applying for an auto loan, review your credit, calculate a realistic budget, save an appropriate down payment, and compare financing options from multiple lenders.
Pay particular attention to APR, loan duration, total repayment, and optional products added to the financing agreement.
Preapproval can also give you valuable information before you begin negotiating with a dealership.
Most importantly, avoid making the decision based only on monthly payment.
A longer loan may make an expensive vehicle appear affordable today while increasing your financial burden for years.
The strongest auto-financing decision balances three things: a reasonable vehicle price, competitive borrowing terms, and a monthly payment that comfortably fits your broader financial life.

Written by Twastia Editorial Team
Twastia Editorial Team shares practical insights about website design, SEO services, Google Ads, content marketing, social media, conversion rate optimization, and digital marketing strategy.
Last updated: Oct 8, 2026
Related posts from Twastia
Explore more useful articles from twastia.com about digital marketing, SEO, websites, ads, content, and growth strategy.