Payment Cards Processor: A Complete Guide for US Businesses in 2026
Accepting credit and debit card payments has become an essential part of running a successful business in the United States. […]
Accepting credit and debit card payments has become an essential part of running a successful business in the United States. Whether you operate a retail store, manage an online business, or provide professional services, customers expect convenient, secure, and reliable payment options.
Behind every successful card transaction is a payment processing system that connects businesses, financial institutions, and payment networks.
Choosing the right Payment cards processor can help businesses manage transactions efficiently, improve customer experiences, and maintain stronger financial operations.
However, with different processing fees, security requirements, and service options available, understanding how payment processing works is important before selecting a provider.
This guide explains the fundamentals of payment card processing, its benefits, common costs, security considerations, and practical tips for choosing a suitable solution for your business.
What Is a Payment Cards Processor?
A payment cards processor is a financial technology service provider that helps manage electronic transactions involving credit cards, debit cards, and other supported payment methods.
It facilitates communication between payment systems and financial institutions to authorize, process, and complete transactions.
When customers purchase products or services using their cards, payment processors help ensure the transaction information reaches the appropriate parties securely.
Processing services may support several business activities, including:
- Credit and debit card transactions
- Online and in-store payments
- Transaction authorization and settlement
- Payment reporting and reconciliation
- Fraud detection and security monitoring
- Recurring payments and subscription billing
Some processors serve merchants directly, while others provide processing infrastructure to banks, card issuers, or acquiring institutions.
Understanding this distinction helps businesses identify the services they actually need.
How Does Payment Card Processing Work?
Although card transactions often appear to happen instantly, several systems work together behind the scenes.
1. Customer Initiates a Payment
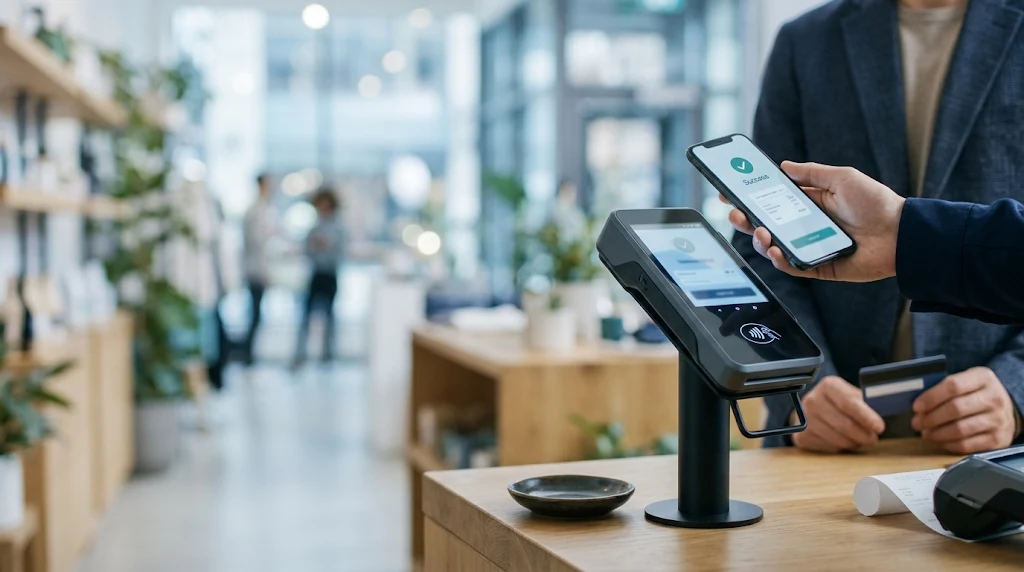
The process begins when a customer presents a credit card, inserts a chip card, taps a contactless device, or enters card information during online checkout.
The payment terminal or online gateway securely collects the necessary transaction details.
2. Transaction Information Is Transmitted
The information travels through the relevant payment processing infrastructure to the appropriate acquiring institution and card network.
The transaction request is then routed to the cardholder’s issuing bank.
3. The Issuing Bank Reviews the Request
The issuing bank evaluates the transaction using factors such as available funds, account status, and fraud prevention controls.
It then approves or declines the transaction.
4. Payment Authorization Is Returned
The authorization response travels back through the processing network.
The business receives confirmation indicating whether the transaction was approved.
5. Clearing and Settlement Take Place
Approved transactions subsequently enter clearing and settlement processes.
Funds are transferred through the relevant financial institutions and made available to the merchant according to the provider’s settlement schedule.
Authorization does not mean the money has already reached the business account.
Why Payment Processing Matters for US Businesses
A dependable payment processing system supports much more than simply accepting credit cards.
It can improve everyday operations while helping businesses deliver convenient purchasing experiences.
Greater Customer Convenience
American consumers use different payment methods depending on their preferences and shopping habits.
Supporting credit cards, debit cards, and compatible digital wallets gives customers more flexibility.
A convenient checkout experience can reduce unnecessary purchasing difficulties, particularly for online stores.
Improved Operational Efficiency
Modern payment processing solutions can automate transaction records, reporting, and reconciliation.
Instead of manually tracking every payment, businesses can access digital reports showing completed transactions, refunds, and settlement activity.
These capabilities simplify financial management and reduce administrative work.
Better Support for Business Growth
As businesses expand, their payment requirements often become more complex.
A scalable processing solution can support additional locations, increased transaction volumes, and new sales channels.
This flexibility is particularly useful for growing retailers, service providers, and ecommerce businesses.
Different Types of Payment Processing Solutions
Payment processing needs vary depending on business size, industry, and purchasing environment.
Understanding the available options makes comparing providers easier.
In-Store Payment Processing
Physical retailers commonly use point-of-sale systems and payment terminals to accept card transactions.
Modern terminals may support EMV chip cards, contactless payments, and compatible mobile wallets.
Restaurants, grocery stores, and service businesses frequently rely on these systems.
Online Payment Processing
Ecommerce businesses use payment gateways and processing services to accept transactions through websites or applications.
A payment gateway securely transmits payment information between the checkout system and the processing infrastructure.
Online solutions may also include fraud screening, saved payment methods, and recurring billing capabilities.
Mobile Payment Processing
Mobile payment solutions allow businesses to accept transactions outside traditional checkout environments.
They can be useful for delivery services, mobile professionals, temporary retail locations, and businesses attending events.
Depending on the provider, mobile processing may involve portable card readers or compatible smartphones.
Financial Institution Card Processing
Banks and card issuers may require specialized platforms for issuing and managing payment cards.
These services can include card lifecycle management, transaction processing, and integration with banking systems.
For example, Network International describes card processing solutions designed for financial institutions, including debit, credit, and virtual card programs. Network International
Key Benefits of Choosing a Reliable Payment Cards Processor
Selecting a suitable provider can contribute to operational stability and customer satisfaction.
Secure Transaction Management
Security is one of the most important considerations when accepting electronic payments.
A reliable provider should support appropriate protections for sensitive cardholder information.
Depending on the service, these may include encryption, tokenization, fraud monitoring, and secure authentication technologies.
Reliable Payment Infrastructure
Payment interruptions can affect sales and customer confidence.
Businesses should evaluate a provider’s system availability, incident response procedures, and technical support.
Reliable infrastructure becomes especially important during busy shopping periods.
Flexible Integrations
Modern businesses often use several digital tools simultaneously.
A compatible payment solution can connect with ecommerce platforms, accounting software, point-of-sale systems, and business applications.
Such integrations can improve reporting consistency and reduce duplicate work.
Useful Transaction Insights
Access to detailed reporting helps businesses understand payment activity.
Transaction dashboards may reveal payment volumes, refund trends, declined transactions, and processing costs.
These insights can support better operational decisions.
Understanding Payment Processing Fees in the USA
Payment processing costs directly affect business profitability.
However, the lowest advertised transaction rate does not always represent the lowest overall cost.
Businesses should understand the main components of processing expenses.
Interchange Fees
Interchange fees are associated with card transactions and generally flow to the card-issuing financial institution.
Their structure can vary depending on card type, transaction characteristics, and applicable network rules.
Network Assessment Fees
Payment card networks may charge fees associated with transactions conducted through their systems.
These costs can form part of the overall amount businesses pay for processing.
Processor Fees
Payment processors charge businesses for the services and technology they provide.
Common pricing structures include flat-rate pricing, interchange-plus pricing, and tiered pricing.
A US Government Accountability Office report identifies these three models as commonly used approaches. files.gao.gov
Additional Service Charges
Depending on the agreement, businesses may encounter monthly account charges, equipment expenses, chargeback fees, or international transaction fees.
Before signing a contract, request a complete pricing breakdown and review termination conditions.
Comparing total estimated monthly costs using your actual transaction patterns is more useful than comparing individual advertised rates.
Payment Security and PCI DSS Compliance
Security should remain a priority for every business accepting card payments.
The Payment Card Industry Data Security Standard, commonly called PCI DSS, establishes technical and operational requirements intended to protect payment account information.
It applies to organizations that store, process, transmit, or can affect the security of relevant cardholder data.
Businesses should understand their responsibilities even when using external payment providers. PCI Security Standards Council+1
Important security practices include using trusted payment technology, restricting access to sensitive information, maintaining updated systems, and reviewing suspicious transactions.
Tokenization and encryption can provide additional protection when implemented appropriately.
Businesses should also ask providers about fraud detection, dispute management, and available security assistance.
How to Choose the Right Payment Cards Processor
Selecting a payment processing provider requires evaluating your business needs rather than focusing exclusively on price.
Evaluate Your Business Requirements
Start by identifying where customers make payments and which payment methods they prefer.
A physical retailer may prioritize terminal compatibility, while an ecommerce business may need seamless website integration.
Compare Complete Pricing
Review transaction fees, monthly charges, hardware costs, and additional service expenses.
Request written pricing information and clarify whether rates can change.
Check Security and Support
Ask about PCI DSS responsibilities, fraud prevention features, customer support availability, and incident handling.
Reliable technical assistance can be particularly valuable when payment systems experience problems.
Review Integration and Growth Options
Choose a solution that works with your existing business tools and can accommodate anticipated growth.
Businesses planning international expansion should also confirm supported countries, currencies, and settlement arrangements.
A provider’s international presence does not automatically mean its services are available to US merchants.
Common Payment Processing Mistakes to Avoid
Businesses sometimes select processors without fully understanding their agreements.
Common mistakes include overlooking additional fees, choosing incompatible equipment, and failing to review settlement schedules.
Another concern is assuming that outsourcing payment processing removes all security responsibilities.
Businesses should also avoid ignoring chargeback management or relying entirely on promotional pricing.
Regularly reviewing processing statements can help identify unexpected charges and operational problems before they become significant.
Future Trends in Card Payment Processing
Payment technology continues to evolve as businesses and consumers adopt more digital purchasing methods.
Contactless payments, digital wallets, and integrated checkout experiences are increasingly important considerations.
Artificial intelligence and advanced analytics are also being used in payment systems to support fraud detection and transaction monitoring.
Meanwhile, embedded payment capabilities allow businesses to incorporate payment functions into their existing applications and platforms.
For US businesses, staying informed about these developments can help maintain competitive and convenient payment experiences.
Frequently Asked Questions
What does a payment cards processor do?
A payment cards processor helps route and manage electronic card transactions between payment systems, card networks, and financial institutions. Its exact responsibilities depend on whether it serves merchants, banks, or other payment providers.
How much does credit card processing cost?
Costs vary by provider, transaction volume, card type, pricing structure, and additional services. Businesses should compare complete processing statements and contract terms rather than relying on a single advertised percentage.
Is a payment gateway the same as a payment processor?
No. A payment gateway securely captures and transmits payment information, while a processor handles transaction communication and related processing functions. Some providers combine both services.
Do small businesses need PCI DSS compliance?
Businesses accepting payment cards generally have applicable payment security obligations. Their specific validation requirements depend on their payment environment and the requirements of relevant payment brands or acquiring institutions.
Can one processor support online and in-store payments?
Yes. Some providers offer integrated or omnichannel solutions for online, mobile, and physical payments. Businesses should confirm compatibility with their existing platforms and equipment.
Conclusion
Choosing the right payment cards processor is an important decision for US businesses seeking secure, convenient, and efficient payment operations.
Understanding how transactions work, comparing complete processing costs, and evaluating security responsibilities can help business owners make informed decisions.
Whether you manage a small retail store, an ecommerce platform, or a growing service business, suitable payment infrastructure can simplify daily operations and improve the customer experience.
Focus on transparent pricing, reliable technology, useful integrations, and responsive support to build a payment system that supports your long-term business goals.

Written by Twastia Editorial Team
Twastia Editorial Team shares practical insights about website design, SEO services, Google Ads, content marketing, social media, conversion rate optimization, and digital marketing strategy.
Last updated: Nov 14, 2026
Related posts from Twastia
Explore more useful articles from twastia.com about digital marketing, SEO, websites, ads, content, and growth strategy.