Commercial Real Estate Bridge Loans: Complete 2026 Guide
Commercial real estate investments often depend on timing. A promising apartment building becomes available, a commercial property needs renovations, or […]
Commercial real estate investments often depend on timing. A promising apartment building becomes available, a commercial property needs renovations, or an existing mortgage approaches maturity before permanent financing is ready. In these situations, waiting for traditional bank approval could mean losing an opportunity.
This is where commercial real estate bridge loans become useful.
Bridge loans provide short-term financing that helps investors purchase, improve, or refinance properties while preparing for a longer-term financial solution. Unlike conventional commercial mortgages, these loans are designed around immediate funding needs and a defined repayment strategy.
For U.S. investors, developers, and business owners, understanding bridge financing can open opportunities while helping manage financial risk.
This guide explains how commercial real estate bridge loans work, their benefits, costs, qualification requirements, and the steps involved in choosing a suitable lender.
What Are Commercial Real Estate Bridge Loans?
Commercial real estate bridge loans are short-term loans secured by commercial property. They provide temporary capital until the borrower can refinance, sell the property, or complete another planned financial transaction.
These loans are commonly used when traditional financing is unavailable or cannot be arranged quickly enough.
For example, an investor might purchase an office building with low occupancy, renovate the property, attract new tenants, and refinance after improving rental income.
Commercial bridge financing can support purchases, renovations, refinancing, and property repositioning.
Loan terms frequently range from approximately six to 36 months, although individual agreements vary.
How Do Commercial Bridge Loans Work?
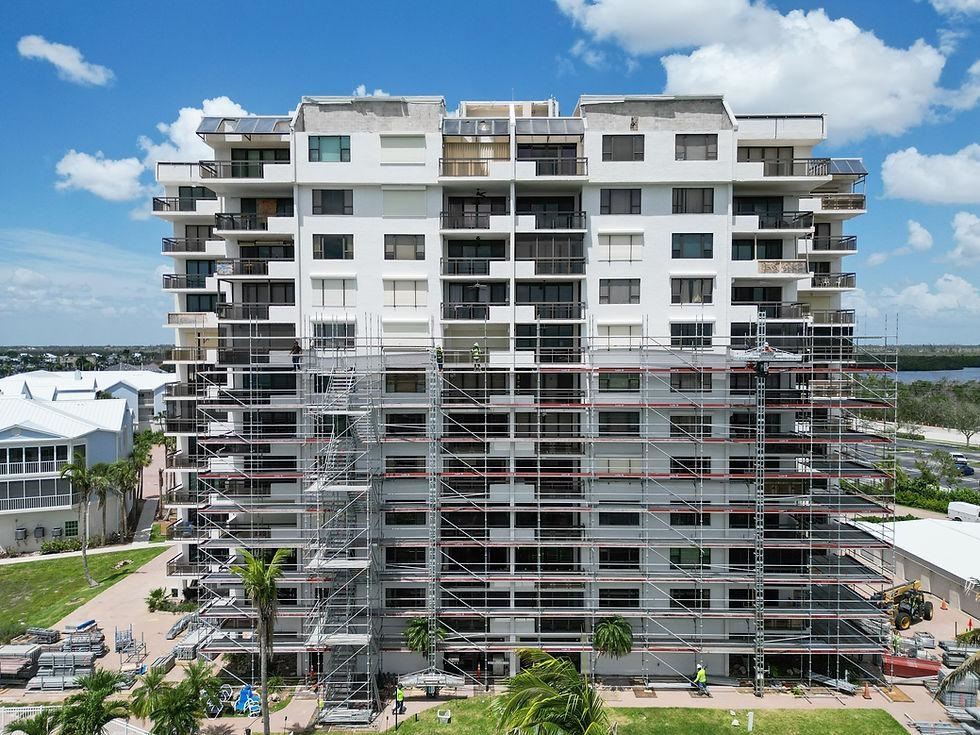
Bridge financing typically begins with an assessment of the property, financing requirements, borrower experience, and proposed repayment strategy.
Unlike long-term mortgages, which often emphasize stable historical income, bridge lenders may consider the property’s future potential alongside its present condition.
Loan Approval and Funding
The lender evaluates property value, current cash flow, existing debt, renovation costs, and the borrower’s investment plan.
If approved, financing may be provided for acquisition, refinancing, or eligible improvement expenses.
Some renovation loans release improvement funds in stages as work progresses.
Interest Payments and Repayment
Many commercial bridge loans use interest-only payments during the loan term.
This structure can reduce monthly debt payments while investors renovate or stabilize their properties.
However, the principal generally remains outstanding and must be repaid when the loan matures.
Repayment commonly occurs through permanent refinancing, a property sale, or another documented source of capital.
When Should Investors Consider Bridge Financing?
Commercial bridge loans are designed for specific financial situations rather than routine long-term borrowing.
Time-Sensitive Property Acquisitions
Competitive commercial real estate transactions sometimes require quick closings.
Traditional lenders may need extensive documentation, appraisals, and underwriting before approving a mortgage.
A bridge lender may offer a faster financing process when the property and borrower meet its requirements.
This can help investors pursue opportunities with short transaction deadlines.
Property Renovation and Repositioning
Investors frequently purchase properties that need improvements before reaching their full income potential.
Bridge financing can provide temporary funding while owners renovate buildings, replace outdated systems, or improve tenant spaces.
After the improvements are complete, the property may qualify for more conventional financing.
Commercial Mortgage Refinancing
Property owners sometimes face approaching loan maturities before securing replacement financing.
A commercial bridge loan may provide additional time to complete leasing, renovations, or refinancing arrangements.
However, investors must verify that the new financing structure remains affordable and that a realistic repayment plan exists.
Improving Occupancy and Rental Income
Properties with significant vacancies may struggle to qualify for conventional commercial mortgages.
Bridge funding can support a lease-up strategy while the borrower works toward stable occupancy and stronger net operating income.
The lender must still evaluate whether the proposed improvement plan is credible.
What Property Types Qualify for Commercial Bridge Loans?
Commercial bridge lenders consider various property categories, depending on their lending guidelines.
Common examples include:
- Multifamily apartment buildings
- Office buildings
- Retail shopping properties
- Warehouses and industrial facilities
- Mixed-use developments
- Self-storage facilities
- Senior housing and healthcare properties
- Student housing developments
Property condition, occupancy, location, and market demand affect eligibility.
For example, commercial real estate bridge loans from Wilshire Finance Partners are designed for several property types, including multifamily, mixed-use, self-storage, healthcare, and light industrial real estate.
The lender states that its commercial bridge financing generally covers loan amounts from $1 million to $10 million.
Individual applications remain subject to underwriting and approval.
Key Features of Commercial Real Estate Bridge Loans
Understanding common lending terms helps investors compare financing proposals more effectively.
Loan-to-Value Ratio
Loan-to-value, or LTV, compares the requested loan amount with the property’s appraised value.
For example, a $1.2 million loan secured by a property valued at $1.8 million represents approximately 66.7% LTV.
Lenders use this measurement to evaluate collateral risk.
Loan-to-Cost Ratio
Loan-to-cost, or LTC, compares financing with total project costs, including eligible acquisition and improvement expenses.
This measurement is particularly relevant for renovation and redevelopment transactions.
Interest Rates and Fees
Bridge financing generally carries higher borrowing costs than conventional long-term mortgages because of its shorter duration and transitional risks.
Rates depend on property type, leverage, borrower qualifications, market conditions, and loan structure.
Additional expenses may include origination fees, appraisal costs, legal fees, and extension charges.
Exit Strategy
An exit strategy explains how the borrower intends to repay the loan.
A credible exit is essential because short-term loans usually require a substantial principal payment at maturity.
Commercial Bridge Loans vs. Traditional Bank Loans
Both financing options serve commercial property investors, but their purposes differ.
| Feature | Commercial Bridge Loan | Traditional Commercial Mortgage |
|---|---|---|
| Loan duration | Usually short-term | Generally longer-term |
| Closing process | Often faster | Often more extensive |
| Primary purpose | Transitional financing | Longer-term property ownership |
| Property condition | May accept transitional assets | Often favors stabilized assets |
| Interest costs | Generally higher | Generally lower |
| Repayment | Often requires refinance or sale | May amortize over time |
Traditional mortgages can be attractive for stabilized properties with predictable income.
Bridge financing may be more suitable when an investor needs flexibility during acquisition, renovation, or refinancing.
The right option depends on the property’s condition and the borrower’s objectives.
How Much Do Commercial Real Estate Bridge Loans Cost?
The total cost of bridge financing includes more than the advertised interest rate.
Investors should evaluate interest payments, loan fees, closing expenses, and potential extension charges.
Example of Bridge Loan Costs
Consider a hypothetical commercial property transaction with these terms:
- Loan amount: $1,200,000
- Annual interest rate: 10%
- Loan duration: 12 months
- Origination fee: 2%
- Payment structure: Interest-only
The monthly interest payment would be approximately $10,000.
Over 12 months, interest expenses would total $120,000.
The 2% origination fee would add another $24,000, producing a combined financing cost of approximately $144,000 before other expenses.
The original $1.2 million principal would still need to be repaid at maturity.
These figures are illustrative, not a current lending offer. Actual rates, fees, and repayment structures vary.
How to Qualify for Commercial Bridge Financing
Although requirements differ among lenders, several factors commonly influence approval.
Property Value and Condition
The commercial property usually serves as primary collateral.
Lenders evaluate its current value, location, marketability, and potential income.
An appraisal or other approved valuation may be required.
Borrower Experience and Financial Strength
Investors with a history of successful property acquisitions or renovations may present stronger applications.
Lenders may also review liquidity, existing obligations, credit history, and available equity.
Business Plan and Exit Strategy
A detailed investment plan should explain how funds will be used and how the property will generate enough value or income to support repayment.
Supporting evidence may include contractor estimates, rent projections, market research, and refinancing assumptions.
Approval is never automatic, even when a property has substantial collateral value.
How to Apply for a Commercial Real Estate Bridge Loan
Step 1: Define Your Financing Needs
Determine the amount required for acquisition, refinancing, improvements, and related expenses.
Include adequate reserves for unexpected costs.
Step 2: Prepare Property Documentation
Gather purchase contracts, financial statements, current rent rolls, operating expenses, property photographs, and renovation budgets where applicable.
Accurate documentation helps lenders understand the transaction.
Step 3: Research Commercial Bridge Lenders
Compare banks offering transitional financing, specialized commercial lenders, and appropriate private credit providers.
Evaluate experience with your property category rather than focusing exclusively on advertised closing speed.
Step 4: Request and Compare Loan Proposals
Ask lenders for written terms explaining interest rates, fees, collateral requirements, repayment schedules, and extension provisions.
Review whether the financing amount covers your complete project needs.
Step 5: Complete Underwriting and Closing
The lender may conduct property valuation, title review, financial analysis, and legal due diligence.
Once all conditions are satisfied, loan documents can be executed and funds disbursed according to the agreement.
Building a Strong Bridge Loan Exit Strategy
A bridge loan is only useful when the borrower can reasonably repay it.
Refinancing Into Permanent Financing
One common approach involves improving occupancy, increasing operating income, and refinancing through a conventional commercial mortgage.
Before accepting bridge financing, investors should estimate whether the completed property will meet likely permanent-lender requirements.
Selling the Property
Some investors plan to renovate and sell the property before maturity.
This approach requires realistic assumptions about market values, selling expenses, and transaction timing.
Preparing a Backup Plan
Property improvements and refinancing arrangements may take longer than expected.
A backup strategy might include available cash reserves or a negotiated extension option.
Extensions are not guaranteed and may involve additional fees.
The Office of the Comptroller of the Currency emphasizes the importance of evaluating refinancing risk, especially when loans involve balloon payments or short-term maturities.
Risks of Commercial Real Estate Bridge Financing
Bridge loans can provide flexibility, but investors should understand their risks.
Higher borrowing costs: Interest and financing fees may reduce investment returns.
Refinancing uncertainty: Future mortgage approval depends on property performance, market conditions, and lender requirements.
Short repayment deadlines: Delays in renovations or leasing may create pressure as maturity approaches.
Market fluctuations: Falling property values or weaker rental demand can affect refinancing and sale opportunities.
Investors should stress-test their projections against higher interest rates, lower occupancy, and unexpected capital expenditures.
A conservative financial plan is generally safer than relying on optimistic appreciation assumptions.
Alternatives to Commercial Bridge Loans
Bridge financing is not suitable for every transaction.
Traditional commercial mortgages may offer more affordable long-term financing for stabilized properties.
Eligible owner-occupied business properties may also qualify for SBA-supported financing.
For example, the SBA 504 program provides long-term financing for qualifying fixed assets, including certain commercial buildings. It is not intended for passive or speculative rental real estate investments.
Investors can also explore joint ventures, additional equity contributions, or other property financing structures.
Comparing alternatives helps determine whether the speed of bridge financing justifies its additional expense.
Frequently Asked Questions About Commercial Real Estate Bridge Loans
1. What Is the Main Purpose of a Commercial Bridge Loan?
A commercial bridge loan provides temporary financing while an investor purchases, improves, sells, or refinances commercial property.
It helps address the gap between an immediate financing need and a longer-term solution.
2. How Long Do Commercial Real Estate Bridge Loans Last?
Many commercial bridge loans have terms ranging from six to 36 months.
The exact duration depends on the lender, property type, borrower qualifications, and planned exit strategy.
3. Are Commercial Bridge Loan Interest Rates Higher?
Generally, yes. Bridge financing often costs more than permanent commercial mortgages because it involves shorter repayment periods and greater transitional risk.
Borrowers should compare total financing expenses, not just interest rates.
4. Can I Get a Bridge Loan for a Vacant Commercial Property?
Possibly. Some lenders finance vacant or partially occupied commercial properties when the borrower presents a credible leasing, renovation, or repositioning plan.
Approval depends on the property’s value, financial projections, and repayment strategy.
5. Do Commercial Bridge Loans Require a Down Payment?
Many transactions require borrower equity, although requirements vary.
Lenders evaluate loan-to-value ratios, project costs, collateral, and the borrower’s financial position when determining financing amounts.
6. Can Bridge Loans Be Used for Multifamily Properties?
Yes. Commercial bridge financing is frequently used for qualifying multifamily properties, particularly buildings undergoing renovation or occupancy improvements.
The property must meet the lender’s eligibility requirements.
7. What Happens if a Bridge Loan Cannot Be Repaid on Time?
Failure to repay at maturity can lead to default, additional charges, or enforcement of the lender’s contractual remedies.
Some agreements permit extensions, but these must meet lender requirements.
Borrowers should develop contingency plans before accepting financing.
8. Are Commercial Bridge Loans Better Than Traditional Mortgages?
Neither option is automatically better.
Bridge loans may be appropriate for transitional properties and time-sensitive transactions, while conventional mortgages are often more suitable for stable, long-term investments.
Conclusion: Choose Commercial Bridge Financing Strategically
Commercial real estate bridge loans can help investors pursue acquisitions, complete improvements, and manage temporary financing challenges.
Their flexibility and potentially faster closing process make them useful for properties that may not currently qualify for permanent financing.
However, higher borrowing costs and short repayment periods require careful planning.
Before applying, evaluate the property’s financial performance, calculate total loan expenses, and develop a realistic exit strategy.
Compare multiple lending proposals and seek qualified financial and legal advice when necessary.
With responsible planning and a suitable investment opportunity, commercial real estate bridge loans can provide the temporary capital needed to move a property toward long-term financial stability.

Written by Twastia Editorial Team
Twastia Editorial Team shares practical insights about website design, SEO services, Google Ads, content marketing, social media, conversion rate optimization, and digital marketing strategy.
Last updated: Oct 13, 2026
Related posts from Twastia
Explore more useful articles from twastia.com about digital marketing, SEO, websites, ads, content, and growth strategy.