Insurtech Explained: How Technology Is Changing Insurance
The insurance industry is experiencing a major digital transformation. From purchasing auto insurance through a smartphone to filing claims online, […]
The insurance industry is experiencing a major digital transformation. From purchasing auto insurance through a smartphone to filing claims online, technology is changing how insurance companies operate and how customers access coverage.
At the center of this transformation is insurtech, a rapidly evolving field that combines insurance services with innovative technology to improve efficiency, customer satisfaction, and risk management.
Traditional insurance processes often involve lengthy paperwork, manual approvals, and complicated claims procedures. Insurtech solutions aim to simplify these activities through artificial intelligence, automation, cloud computing, and digital platforms.
For consumers, this can mean easier policy comparisons, convenient account management, and faster communication. For insurance companies, it creates opportunities to streamline operations and improve decision-making.
In this guide, we’ll explore what insurtech means, how it works, the technologies driving its growth, its benefits and challenges, and the trends shaping the U.S. insurance market.
What Is Insurtech?
Insurtech is a combination of the words insurance and technology. It describes the use of modern digital tools and innovative business models to improve how insurance products are developed, distributed, managed, and serviced.
Insurtech isn’t limited to startup companies. Established insurance carriers, independent agencies, brokers, and technology providers also use these solutions.
According to the National Association of Insurance Commissioners (NAIC), insurtech helps consumers purchase, understand, and manage insurance through convenient digital experiences.
NAIC
Insurtech vs. Traditional Insurance
Traditional insurance operations frequently rely on manual document reviews, telephone communication, and separate administrative systems.
Insurtech introduces digital applications, automated workflows, connected data, and online self-service tools.
However, the goal isn’t necessarily to eliminate human professionals. Many solutions help insurance agents and underwriters work more effectively while giving customers easier access to support.
How Does Insurtech Work?
Insurtech combines software, data, and automated processes to improve different stages of the insurance customer journey.
1. Digital Insurance Applications
Customers can research insurance products, compare options, and submit applications through websites or mobile apps.
Instead of completing physical forms, applicants enter information into secure online systems.
Some platforms use automation to validate information and prepare quotes more quickly.
2. Automated Underwriting
Underwriting involves evaluating insurance risks and determining whether coverage can be offered under specific terms.
Insurtech platforms can help underwriters organize applications, assess relevant information, and identify cases requiring additional attention.
Machine learning tools may support risk analysis, but insurers remain responsible for their decisions and compliance obligations.
3. Digital Policy Management
After purchasing coverage, customers may access policy documents, update contact details, review payment information, or request changes through online portals.
These tools can reduce routine administrative work and improve access to information.
4. Streamlined Claims Processing
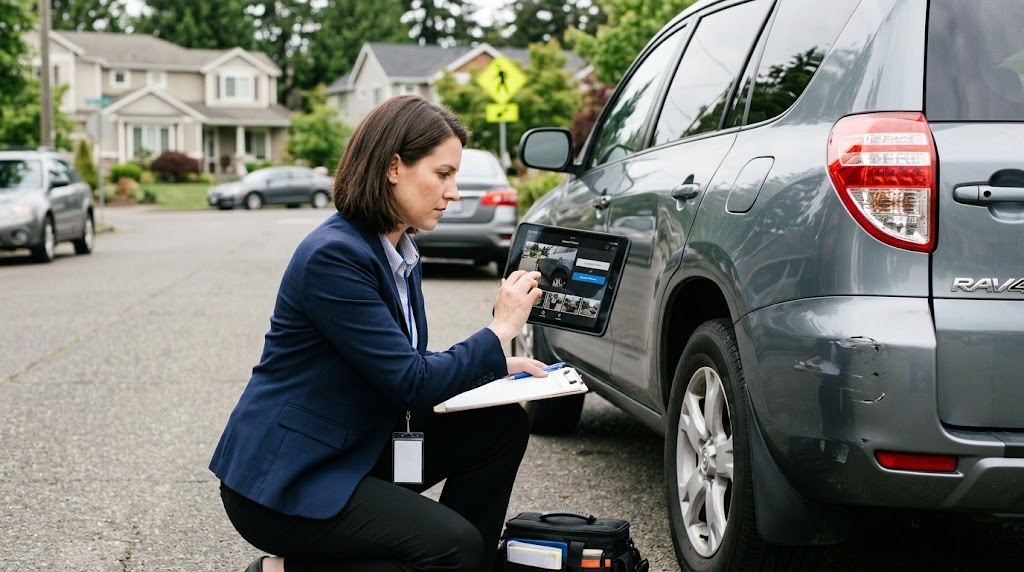
Digital claims platforms allow policyholders to submit photographs, upload documents, report incidents, and track claims electronically.
Automation can route information to appropriate teams and support faster reviews.
Complex or disputed claims may still require experienced adjusters and manual investigation.
Key Technologies Driving Insurtech Innovation
Several technologies are helping reshape the insurance industry.
Artificial Intelligence and Machine Learning
Artificial intelligence is among the most influential technologies used in modern insurance systems.
AI can help analyze information, classify documents, identify unusual claim patterns, and assist customer service teams.
Machine learning models can also support underwriting, pricing analysis, and fraud detection.
The NAIC identifies underwriting, customer service, claims management, and fraud prevention as important applications of AI in insurance.
NAIC
However, automated decisions require appropriate oversight because inaccurate data or biased models can create unfair outcomes.
Big Data and Predictive Analytics
Insurance companies work with large amounts of information involving customers, claims, property characteristics, and historical losses.
Advanced analytics help identify patterns and support business decisions.
For example, property insurers may analyze weather-related risks when developing risk-management strategies.
Predictive models can also help identify operational problems before they become more costly.
Internet of Things (IoT)
The Internet of Things refers to connected devices that collect and exchange information.
In insurance, these devices may include vehicle telematics, smart-home leak detectors, connected security equipment, and eligible wearable devices.
A water sensor, for instance, may alert a homeowner to a leak before extensive damage occurs.
Some auto insurers also offer usage-based programs that consider driving-related information when determining premiums, subject to applicable rules.
Cloud Computing and Automation
Cloud platforms help insurance organizations access applications and data across departments and locations.
Workflow automation can handle repetitive activities, such as routing documents, generating reminders, and updating policy records.
These capabilities support collaboration between agents, carriers, claims professionals, and customer service teams.
Major Benefits of Insurtech for Insurance Companies and Customers
Insurtech provides potential advantages to both insurers and policyholders.
Improved Customer Experience
Digital platforms make it easier for customers to manage coverage without relying exclusively on office visits or telephone calls.
Self-service tools, electronic documents, and automated notifications can improve convenience.
Greater Operational Efficiency
Automation helps reduce manual data entry and repetitive administrative work.
Employees can focus more attention on complicated claims, specialized underwriting, and customer relationships.
Faster Claims Communication
Mobile claims tools make incident reporting more convenient and can reduce delays caused by incomplete paperwork.
Faster information collection doesn’t guarantee faster settlement, but it can improve the initial reporting process.
More Personalized Insurance Products
Data analysis can help insurers develop products suited to specific customer needs.
For example, some programs use driving behavior or connected-device information to provide alternative approaches to pricing.
Consumers should understand which information is collected and how it may affect their coverage.
Real-World Examples of Insurtech
Insurtech applications are already part of everyday insurance experiences across the United States.
Digital Auto Insurance
An auto insurance customer may request a quote, upload vehicle information, and access proof of insurance through a mobile application.
After an accident, the same customer may photograph the damage and submit an initial claim electronically.
Technology-Enabled Claims Management
In a case highlighted by Salesforce, Farmers Insurance used a digital claims platform to reduce initial loss-reporting time from approximately 12 minutes to three minutes.
The example illustrates how streamlined reporting can improve a specific workflow, although results vary between insurers and systems.
Salesforce
Smart Property Insurance
Connected home sensors can detect certain risks, including water leaks or unusual environmental conditions.
Early warnings may help homeowners respond before damage becomes more severe.
These technologies demonstrate how insurance innovation can support prevention as well as financial protection.
How Insurtech Is Changing Insurance Business Models
Insurtech isn’t just introducing new software. It is also changing how insurance products reach consumers.
Embedded Insurance
Embedded insurance offers coverage during the purchase of another product or service.
For example, a customer buying electronics or booking travel may be offered an insurance product during checkout.
This approach can simplify purchasing, but customers should still review policy exclusions, pricing, and eligibility.
Usage-Based Insurance
Usage-based insurance considers certain measurable activities, particularly in auto insurance.
Participating customers may share driving data through mobile applications or connected devices.
Pricing outcomes depend on the insurer’s program, the collected information, and applicable regulations.
Digital-First Insurance Services
Digital-first providers emphasize online applications, automated communication, and mobile account management.
Traditional insurers are also adopting similar technology rather than leaving digital innovation entirely to startups.
Challenges and Risks of Insurtech
Despite its advantages, insurance technology introduces important challenges.
Data Privacy and Cybersecurity
Insurance companies may handle sensitive financial, personal, medical, and property-related information.
Organizations must protect this information through appropriate security controls, access restrictions, and responsible data-management practices.
Cyberattacks and data breaches can damage customer trust and create significant operational risks.
Algorithmic Bias
AI models may produce unfair outcomes when training data, model design, or implementation introduces bias.
For example, automated risk assessment must be evaluated carefully to avoid unfair discrimination.
Complex System Integration
Established insurers often operate older technology systems.
Connecting new digital platforms with existing policy, billing, and claims software can require substantial planning and investment.
Maintaining Human Support
Not every insurance issue can be resolved through a chatbot or automated decision.
Customers dealing with serious accidents, major property losses, or disputed claims may need direct assistance from an experienced professional.
Insurtech Regulation in the United States
Insurance regulation in the United States is primarily administered at the state level.
Companies adopting new technologies must consider applicable insurance laws, consumer protection requirements, privacy obligations, and cybersecurity standards.
In December 2023, the NAIC adopted its Model Bulletin on insurers’ use of artificial intelligence systems.
The bulletin establishes regulatory expectations concerning AI governance, responsible use, and consumer protection. Individual states determine how to adopt or implement relevant guidance.
content.naic.org
For insurers, responsible innovation means balancing technological efficiency with fairness, transparency, security, and accountability.
Important Insurtech Trends Shaping 2026 and Beyond
Several developments are influencing the future of insurance technology.
Generative AI in Insurance Operations
Generative AI can help summarize lengthy insurance documents, assist service representatives, and organize information from customer communications.
These capabilities may reduce routine workloads.
However, AI-generated information requires verification, particularly when it affects coverage interpretation or claim decisions.
Predictive Risk Prevention
Insurance technology is increasingly supporting earlier risk identification.
Connected sensors, predictive analytics, and weather data may help insurers and policyholders take preventive action.
Personalized Digital Experiences
Consumers increasingly expect convenient digital services, clear information, and communication through their preferred channels.
Insurance companies are responding by improving mobile experiences and integrating customer information across departments.
Increased Attention to Responsible AI
As insurers adopt sophisticated models, regulators are examining issues involving data quality, fairness, transparency, and accountability.
The NAIC’s 2026 insurtech guidance emphasizes both innovation and continued consumer protection.
NAIC
How Insurance Companies Can Choose the Right Insurtech Solutions
Selecting insurance technology requires more than choosing software with impressive features.
Organizations should begin by identifying a clear business problem.
Evaluate Business Requirements
Determine whether the priority is faster claims processing, better customer communication, improved underwriting, or reduced administrative workload.
Specific goals make it easier to evaluate competing solutions.
Review Security and Compliance
Assess vendor security practices, data-handling policies, integration capabilities, and relevant regulatory requirements.
Insurance organizations should also understand how external technology providers use and protect customer information.
Measure Results
Track meaningful indicators such as processing time, customer satisfaction, error rates, and operating costs.
Pilot programs can help businesses identify problems before expanding a new platform.
Consider Salesforce Insurance Technology Solutions
Salesforce provides customer relationship management and insurance-related technology solutions designed to connect information, support automation, and improve customer interactions.
Its guide to insurtech explains how insurers and brokers can use digital tools to modernize business processes.
Organizations evaluating insurance technology can use these resources to better understand CRM integration, workflow automation, and connected customer experiences.
Frequently Asked Questions About Insurtech
1. What does insurtech mean?
Insurtech combines insurance and technology. It describes digital tools and innovative business models that improve insurance purchasing, underwriting, policy management, claims processing, and customer service.
2. Is insurtech the same as fintech?
No. Fintech is a broader category covering financial technology, including digital payments, banking, and investment services. Insurtech specifically focuses on the insurance industry and is commonly considered part of the wider fintech ecosystem.
3. How does insurtech benefit customers?
Customers may benefit from convenient online applications, digital policy access, faster communication, automated updates, and easier claims submission.
4. What technologies are used in insurtech?
Common technologies include artificial intelligence, machine learning, cloud computing, big data analytics, mobile applications, workflow automation, and Internet of Things devices.
5. Is insurtech replacing traditional insurance companies?
Not necessarily. Many established insurers use insurtech solutions to improve existing services. Startups and traditional insurance companies can compete, collaborate, or use similar technology.
6. Can insurtech reduce insurance premiums?
Certain technologies may help insurers reduce operating expenses or price risks differently. However, lower premiums are not guaranteed. Insurance prices depend on coverage, risk characteristics, underwriting practices, and regulatory requirements.
7. How is artificial intelligence used in insurance?
AI can assist with underwriting analysis, document classification, customer service, fraud detection, and claims review. Appropriate human oversight remains important.
8. What is the future of insurtech?
The industry is likely to expand its use of AI-assisted workflows, connected devices, digital distribution, and predictive analytics while facing increased expectations around cybersecurity, transparency, and responsible decision-making.
Conclusion: Why Insurtech Matters for the Future of Insurance
Insurtech is transforming the insurance industry by making many insurance processes more digital, connected, and efficient.
From artificial intelligence and automated underwriting to mobile claims management and personalized services, technology is creating new opportunities for insurance companies and policyholders.
However, successful insurance innovation requires more than automation. Organizations must protect customer information, maintain regulatory compliance, and ensure that technology supports fair and reliable decisions.
For insurers, brokers, and business owners seeking to understand digital transformation, exploring established technology platforms is a useful starting point.
Learn more through Salesforce’s insurtech guide and discover how modern insurance technology can support better customer experiences and more efficient operations.
Disclaimer: This article provides general educational information about insurance technology and is not legal, financial, or insurance coverage advice. Requirements and insurance products vary by provider and U.S. state.

Written by Twastia Editorial Team
Twastia Editorial Team shares practical insights about website design, SEO services, Google Ads, content marketing, social media, conversion rate optimization, and digital marketing strategy.
Last updated: Oct 11, 2026
Related posts from Twastia
Explore more useful articles from twastia.com about digital marketing, SEO, websites, ads, content, and growth strategy.